
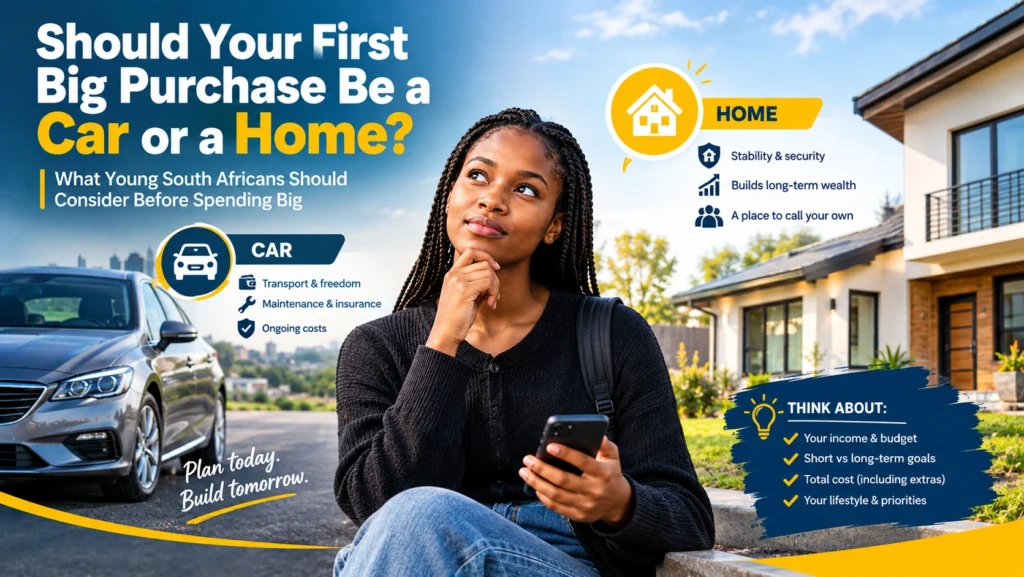
Should your first big purchase be a car or a home? .Your first decent salary can create a strange kind of pressure.
After years of studying, searching for work or surviving on temporary income, you finally start earning enough to think beyond the next payday. Then the questions arrive: Should you finance a car? Should you start saving for a house? Should you move out? Should you invest instead?
For many young South Africans, the car-versus-home decision is particularly difficult because both purchases can change your life — but in very different ways.
A car can make it possible to accept a job that is far from home. It can save hours on public transport and give you more freedom. A home can provide stability and allow you to build equity over time.
But both can also become financial traps.
The biggest mistake is looking at a R5,000 car instalment or a R10,000 home-loan repayment and thinking, “I can afford that.”
The real question is: What will this purchase cost me every month after everything is included — and what will I have to give up to pay for it?
That is why the decision should not be based on status, pressure from friends or what a bank says you qualify for.
It should be based on your income, job security, savings, location, family responsibilities and five-year plans.
Understanding the Car vs Home Decision
A car and a home are not financially identical.
A vehicle is generally a depreciating asset. It normally becomes worth less as it ages, while you continue paying for insurance, fuel, maintenance and repairs.
A property can potentially build equity as you repay the loan, but owning a home also comes with significant ongoing costs and does not guarantee a profit.
This distinction matters.
A R300,000 car does not necessarily mean you have gained R300,000 of wealth. Its market value can fall considerably while you are still paying the finance agreement.
With a home, part of your bond repayment may build equity, but the property also needs maintenance and can involve rates, insurance, levies and other costs.
So instead of asking:
“Which asset is better?”
Ask:
“Which financial commitment makes the most sense for the stage of life I am currently in?”
ALSO APPLY FOR: WCG Learnership 2026
ALSO APPLY FOR: Dwarsrivier Chrome Learnership 2026
Why This Issue Matters
Your first major purchase can determine how much financial freedom you have for years.
Imagine someone earning R25,000 a month after deductions.
They take a vehicle because they want something impressive and end up spending:
- R5,000 on the instalment
- R1,400 on insurance
- R2,000 on fuel
- R600 on maintenance
- R300 on miscellaneous vehicle costs
The car is now consuming around R9,300 every month.
The person may technically afford the instalment, but the vehicle is taking a much larger bite out of their income than expected.
Now imagine the same person trying to save a home deposit while paying those costs.
The issue is not that buying the car was automatically wrong. The issue is that the total financial impact was never considered.
The same problem happens with property.
Someone may qualify for a large home loan but discover afterwards that rates, insurance, maintenance, utilities and levies make the monthly budget uncomfortable.
This is how people become house-rich or car-rich but cash-poor.
Your first major purchase should ideally leave you with enough financial breathing room to handle life’s surprises.
Should Your First Big Purchase Be a Car or a Home?
There is no universal winner.
Your circumstances should determine the answer.
When a car may make more sense
A car could be a practical first purchase if:
- Your job requires reliable transportation.
- Public transport makes getting to work extremely difficult.
- You regularly work night shifts or travel between locations.
- A car could allow you to accept better employment opportunities.
- You live far from major transport routes.
- You have stable income and emergency savings.
- You can afford the vehicle without sacrificing essential financial goals.
For someone whose income depends on getting to different workplaces, a reliable vehicle can be more than a lifestyle purchase.
It can be a career-enabling tool.
But that does not mean you need a luxury vehicle.
A reliable, affordable used car may accomplish the same objective while leaving more money available for saving and investing.
When Buying a Home May Make More Sense
Property ownership may fit your circumstances when:
- Your employment or household income is reasonably stable.
- You expect to remain in the same area for several years.
- You have accumulated a meaningful deposit.
- You have emergency savings separate from your deposit.
- Your existing debt is manageable.
- You understand the additional costs of ownership.
- The property fits your long-term lifestyle rather than simply your current salary.
A home can offer stability and potentially build equity over time.
But buying property should not be treated as an automatic wealth-building strategy.
The location, purchase price, financing costs, maintenance requirements and length of ownership all matter.
ALSO READ ABOUT: Buying vs Renting
What If You Cannot Comfortably Afford Either?
This is where good financial planning becomes more important than social pressure.
You do not have to make a major purchase simply because you have started earning.
Sometimes the best decision is to spend another year preparing.
That could mean:
- Paying off expensive debt.
- Building an emergency fund.
- Improving your credit profile.
- Saving a larger deposit.
- Increasing your income.
- Learning about home loans and vehicle finance.
- Comparing insurance costs.
- Building investments alongside your savings.
- Finding cheaper transport.
Waiting is not necessarily falling behind.
It can mean you are buying yourself financial flexibility.
Step 1: Know Your Real Affordability
Start with your take-home salary.
Do not use your gross salary.
Then calculate your essential monthly expenses.
| Monthly expense | Example |
|---|---|
| Take-home income | R25,000 |
| Rent | R6,000 |
| Food | R3,000 |
| Utilities | R1,500 |
| Existing debt | R2,000 |
| Family commitments | R1,500 |
| Other essentials | R2,000 |
| Remaining amount | R9,000 |
The R9,000 remaining is not automatically available for a car or home repayment.
You still need to account for saving, emergencies, insurance and unexpected expenses.
This is why affordability calculators should be treated as starting points rather than permission to borrow the maximum amount offered.
Step 2: Calculate the Real Cost of the Car
The monthly instalment is only the beginning.
Before signing a vehicle finance agreement, calculate:
- Monthly instalment
- Deposit
- Interest
- Insurance
- Fuel
- Maintenance
- Tyres
- Licensing
- Parking
- Tolls
- Repairs
- Optional extras
Example
Suppose the finance repayment is R5,000.
Your real monthly cost might look more like this:
| Car cost | Example monthly amount |
|---|---|
| Finance | R5,000 |
| Insurance | R1,300 |
| Fuel | R2,000 |
| Maintenance provision | R600 |
| Licence/other costs | R200 |
| Total | R9,100 |
These are illustrations, not quotations. Actual costs vary considerably.
The important lesson is simple:
Never make a car decision based only on the instalment.
Step 3: Calculate the Real Cost of a Home
The same principle applies to property.
Your monthly housing cost could include:
- Bond repayment
- Municipal rates
- Home insurance
- Levies
- Electricity
- Water
- Security
- Maintenance
- Repairs
- Internet
- Garden or household services
You may also have substantial upfront costs depending on the transaction.
Before buying, calculate the total cost of ownership, not just the bond.
A property that looks affordable on paper can become uncomfortable once all the additional expenses are included.
ALSO READ ABOUT: From Bursary Student to Investor
Step 4: Ask What Problem You Are Actually Solving
This is one of the most useful questions you can ask.
If you want a car, ask:
“What problem will this car solve?”
Is it:
- A long commute?
- Unreliable public transport?
- A job requiring travel?
- Family responsibilities?
- Safety concerns?
- Access to opportunities?
If the answer is simply, “I want a nicer car because my friends have one,” consider waiting.
If you want a home, ask:
“Why do I want to own property now?”
Is it:
- Long-term stability?
- Family needs?
- Avoiding rising rent?
- A suitable investment?
- Establishing yourself in one location?
Understanding the reason behind the purchase can prevent emotional financial decisions.
Step 5: Think About Your Next Five Years
Your current situation is not enough.
Think about where your life may be heading.
For example, buying a property can become complicated if you expect to relocate for work within two years.
Similarly, taking on an expensive car can make it harder to save for a deposit.
Ask yourself:
- Could my job require relocation?
- Am I planning further studies?
- Could my income change?
- Am I likely to get married or start a family?
- Do I support relatives?
- Am I planning to start a business?
- Will I need to move closer to work?
- Do I expect my transportation needs to change?
You do not need to predict your entire future.
You simply need to avoid making a major financial commitment that conflicts with your most obvious plans.
Step 6: Compare the Opportunity Cost
This is an overlooked part of the decision.
Suppose an expensive vehicle costs you an additional R4,000 every month compared with a cheaper alternative.
That R4,000 has an opportunity cost.
Over one year, that is:
R4,000 × 12 = R48,000
Over five years, ignoring investment returns and other changes, it represents:
R240,000.
That money could potentially have gone towards:
- A home deposit
- Retirement savings
- An emergency fund
- Education
- Business capital
- Paying off debt
- Investments
The point is not that investing the money would definitely produce a particular return.
The point is that every major financial commitment closes some doors while opening others.
Step 7: Use the “Three-Bucket” Test
Before buying either asset, divide your money into three conceptual buckets.
Bucket 1: Living
This covers:
- Housing
- Food
- Transport
- Utilities
- Family commitments
- Insurance
Bucket 2: Safety
This includes:
- Emergency savings
- Insurance protection
- Short-term financial reserves
Bucket 3: Building Wealth
This includes:
- Retirement contributions
- Long-term investments
- Home deposits
- Education
- Business opportunities
A major purchase becomes risky when Bucket 1 consumes so much income that there is nothing left for Buckets 2 and 3.
ALSO RSED ABOUT: What Is Compound Interest
A Practical Car vs Home Comparison
| Factor | Buying a Car | Buying a Home |
|---|---|---|
| Main purpose | Transportation | Housing/stability |
| Typical financing | Vehicle finance | Home loan |
| Value over time | Usually depreciates | Can rise or fall |
| Major ongoing costs | Fuel, insurance, maintenance | Rates, insurance, maintenance, utilities |
| Flexibility | Relatively high | Lower |
| Career mobility | Usually supports it | Can sometimes restrict it |
| Emergency fund needed | Yes | Yes |
| Deposit | Often useful | Often substantial |
| Long-term commitment | Usually shorter | Usually much longer |
| Main risk | Depreciation and ongoing costs | Large debt and ownership costs |
Neither column should automatically determine your decision.
Your circumstances do.
Best Practices Experts Recommend
A financially sensible first purchase generally follows a few principles.
Buy for usefulness, not appearance
Your first car does not need to communicate your salary to everyone around you.
Keep borrowing manageable
A lender’s maximum approval is not necessarily your personal affordability limit.
Maintain an emergency fund
Do not spend your entire savings account on a deposit.
Compare total costs
Always calculate interest, insurance, maintenance and other recurring expenses.
Protect your future flexibility
If your career is still developing, avoid unnecessary financial commitments that could make relocation difficult.
Shop around
Compare financing, insurance, property costs and alternatives before signing.
Consider the cheaper version of the same goal
Instead of asking:
“Can I afford this?”
also ask:
“Can I achieve the same objective for less?”
That question can save you thousands of rand.
Mistakes People Often Make
1. Buying according to salary
A salary increase does not mean your lifestyle must increase immediately.
2. Focusing on monthly instalments
A low instalment can hide a long repayment period and higher overall financing costs.
3. Forgetting irregular expenses
Car services, tyres and home repairs may not happen every month, but they still need to be funded.
4. Emptying savings for the deposit
A large deposit is not helpful if you have nothing left when an emergency happens.
5. Buying property because “rent is wasted money”
Rent pays for housing and flexibility. Home ownership also carries costs that do not directly become equity.
6. Choosing a car for status
A car should solve a transportation problem before it becomes a lifestyle statement.
7. Ignoring job security
Large debt commitments become harder to manage when income is uncertain.
8. Forgetting opportunity cost
The money committed to a vehicle or home cannot simultaneously be used for another financial goal.
ALSO READ ABOUT: ETF vs Unit Trust
A Simple Decision Test Before You Sign
Give yourself a cooling-off period before making the final decision.
Ask these questions:
1. Can I afford the purchase if my expenses increase?
2. Could I survive several months of reduced income?
3. Will I still be able to save every month?
4. Do I have emergency savings after making the purchase?
5. Have I calculated the complete cost rather than the instalment?
6. Does this purchase support my five-year plans?
7. Am I buying because I need it or because I feel pressure to have it?
8. Is there a cheaper way to solve the same problem?
If the answers make you uncomfortable, pause.
There is nothing wrong with waiting.
Frequently Asked Questions
Should I buy a car before a house?
It depends on your circumstances. If reliable transportation is essential to maintaining or improving your income, a reasonably priced car may be a practical first purchase. If transport is manageable and you have stable employment and a realistic path to home ownership, prioritising a property deposit may fit your goals better.
Is a car a bad first investment?
A car is generally not the same type of wealth-building asset as a productive investment. It usually depreciates and creates ongoing expenses. However, a vehicle can still be financially useful if it enables employment, reduces commuting difficulties or supports income generation.
Should I wait until I can pay cash for a car?
Not everyone needs to pay cash, and vehicle finance can have a legitimate purpose. The important issue is whether the financing cost fits your budget and whether the vehicle is reasonably priced. Compare the total amount payable rather than focusing only on the monthly instalment.
Is buying a home always financially better than renting?
No. The answer depends on the property price, financing costs, maintenance, location, length of ownership and your circumstances. Renting can provide flexibility, while buying can provide ownership and potential equity growth. Both have financial costs and benefits.
Final Advice: Your First Big Purchase Should Buy You More Freedom, Not Less
The biggest lesson from the car-versus-home debate is that there is no prize for becoming heavily indebted as quickly as possible.
Your first big purchase should fit into a broader financial plan.
If a car helps you reach employment, study opportunities or income-generating activities, it can be an important tool. But you do not need the most expensive vehicle you qualify for.
If buying a home fits your location, income and long-term plans, ownership may help provide stability and build equity over time. But you should understand the full cost before committing to a bond.
And if your finances are not ready for either, waiting can be a financially productive decision.
Build the emergency fund. Reduce expensive debt. Save consistently. Improve your income. Research the market. Then buy when the numbers make sense.
The goal is not simply to say, “I own a car,” or “I own a house.”
The real goal is to reach a point where your major purchase improves your life without controlling your entire monthly budget.
Before making the decision, remember this simple rule:
Buy the asset that solves a genuine problem, fits your long-term plans and leaves enough room for you to keep building wealth afterwards.
That is a much stronger starting point than buying something simply because it looks like success.